Lowball Offers: What Counts As Low & How To Make One
Oct 22, 2026
Written by
Alex Martinez, Founder & CEO, Real Estate Skills. Has wholesaled and flipped houses for over 14 years, been part of 1,000+ real estate transactions, and personally acquired 55+ residential investment properties. Has trained 6,000+ investors nationwide.
Reviewed by
Ryan Zomorodi, Co-Founder & COO, Real Estate Skills. Reviewed the offer strategy, worked numbers, and legal points in this guide.
Publication history: Originally published May 19, 2020. Updated October 2026 with current market data, a worked offer example, breakdowns of real listing-agent calls, offer scripts, and new guidance for sellers. Offer strategy, figures and legal points reviewed by Ryan Zomorodi, Co-Founder & COO of Real Estate Skills.
Lowball offers are bids that come in well below the seller's asking price, usually 10% to 30% under, depending on the market. They're more normal than most beginners think: 60.5% of U.S. homes sold below their original asking price in September 2026, according to Redfin.
Most beginners are scared to make a lowball offer. They picture the listing agent laughing, the seller getting offended, and their name getting passed around town as the investor who insults people. So they offer close to asking, overpay, and then wonder why there's no profit left in the deal.
Here's what actually happens when you do it right. I've submitted thousands of offers in 14 years of wholesaling and flipping houses, and the agents who take a low number seriously aren't reacting to how low it is. They're reacting to whether you can back it up. A low offer with the repairs, the comps and a clean cash close behind it is just business. A low offer pulled out of thin air is the one that gets ignored.
In this guide, I'll show you what counts as a lowball offer in 2026, how to calculate yours with real numbers, the exact questions and words my team uses with listing agents, and what to do if you're the seller on the other side of one. If you want to run your own numbers as you read, grab my free deal calculator here.
What Is A Lowball Offer?
A lowball offer is an offer well below what the seller is asking. Lowballing is the act of making one: offering a price below the seller's asking price to start a negotiation or because the property is overpriced. It's legal, it's common, and the seller is free to say no.
The asking price (also called the list price) is the number the seller puts on the listing. It's what they hope to get, not what the house is worth. Lowballing is essentially offering a price below a seller's asking price. You'll see it spelled "lowball," "low ball" and "low-ball." They all mean the same thing.
It works the same way anywhere people haggle. Offer $40 for a bike with a $60 tag at a garage sale, and you've lowballed the seller. In real estate the numbers just have more zeros, and the stakes are higher on both sides.
Here's the distinction most people miss: there's a big difference between an offer that's below asking and an offer that's below value. Sellers price their homes on hope, memories and whatever their neighbor's house sold for. If a house is listed for more than it's worth in its current condition, an offer at its real value will look like a lowball even though it's simply the correct price. Most of the "lowball" offers I make fall into that category.
That's why investors make so many of them. When you learn how to flip a house, you learn fast that you make your money when you buy, not when you sell. Flippers have to leave room for repairs and profit. Rental investors using the BRRRR method need the numbers to work after a refinance. Wholesalers like me put a house under contract and sell that contract to a cash investor, so the price has to leave room for their profit and my fee. Regular homebuyers lowball too, mostly in slow markets where homes sit unsold.
So if you're worried a low offer will get you in trouble, it won't. An offer is just an offer. The seller can accept it, counter it or reject it, and you move on to the next house.
What Is Considered A Lowball Offer On A House?
Most real estate pros consider an offer a lowball when it's 10% to 30% below the asking price, and many draw the line around 15%. The real answer depends on your market: in slow markets big discounts are routine, while in competitive ones any offer under asking can look low.
There's no official number. "Lowball" is whatever the seller feels is too low, and that feeling changes with the market. Still, you need a working guide before you write an offer, so here's how a discount usually reads on a house listed at $300,000:
| How Far Below Asking | Your Offer | How It Usually Reads |
|---|---|---|
| 5% | $285,000 | Normal negotiating in most markets |
| 10% | $270,000 | Starts to look low in balanced or competitive markets |
| 15% | $255,000 | Where many agents draw the lowball line |
| 20–30% | $240,000–$210,000 | A clear lowball. You'll need repairs, a long time on the market or a motivated seller to justify it. |
Treat that table as a rough guide, not a rule. Two numbers show why.
First, the typical discount is small. In August 2026, the average U.S. home sold for 96.4% of its original asking price, according to Redfin. That means the typical buyer got about 3.6% off. A 15% offer asks for roughly four times the normal discount. That isn't wrong, but it tells you why you need a reason behind the number.
Second, "normal" swings wildly by location. In August, 85% of homes in West Palm Beach sold below their asking price, while in San Francisco only 30% did. A 15% discount is a regular Tuesday in one of those markets and an insult in the other.
So the percentage matters less than the question underneath it: is your offer below what the house is worth, or just below what the seller is asking? Before you decide how low to go, pull your real estate comps (recently sold homes similar to yours, nearby). I look at what's active, pending and sold within about half a mile over the last six months. If those comps say the house is worth $255,000 in its current condition, an offer at $255,000 isn't a lowball. It's the market price, and the listing is overpriced.
That's also your answer if you're worried about insulting the seller. A number you can back up with sold comps and a list of repairs is a business proposal. A number with nothing behind it is the kind that gets an offended "no."
Lowball Offer Example
Here's a lowball example: a house listed at $300,000 that would be worth $300,000 only after $30,000 of repairs. An investor who offers $220,000, about 27% below asking, is making a lowball offer, but the math shows it's what the house is worth as-is to someone who has to fix it.
This is the most common lowball situation I see, and it's the one beginners get wrong in both directions. They either offer close to asking because they're scared, or they throw out a random low number they can't explain.
The house is listed at $300,000. The kitchen and bathroom need to be redone, the AC doesn't work, and the floors are shot. The comps say a fully renovated version of this house sells for about $300,000. In other words, the seller has priced it as if the work were already done.
💡 What This House Is Actually Worth To An Investor
- After repair value (ARV): what it sells for once fixed up, based on sold comps. $300,000
- Minus repairs (kitchen, bathroom, AC, flooring). −$30,000
- Minus the costs to buy, hold and resell (closing costs, taxes, insurance, utilities, agent commissions). About −$25,000
- Minus the investor's profit for taking on the risk and the work. −$25,000
- The most an investor can pay: $220,000, about 27% below the asking price.
In this example, buying, holding and selling costs run about 8% of the fixed-up value. Yours will depend on your market, your timeline and your loan. Results vary.
By the table in the last section, $220,000 is a clear lowball. But look at what it actually is: the house's value minus the work it needs. The seller isn't being robbed. They're being shown what a house in this condition sells for to the people who can actually buy it, and many regular buyers either can't take on a $30,000 project or don't want to.
The proof usually comes straight from the listing agent. One question in my discovery call is, "What would you say this home could be worth in its best possible condition, once it's renovated?" If the agent names a number close to the list price, they've just told you the listing is priced as if the work were done. That's your reason for the low number, and you didn't have to argue for it.
How you deliver an offer like this matters as much as the number. I'll show you the exact process and words in the sections on making the offer and what to say.
When Should You Make A Lowball Offer?
Make a lowball offer when the situation gives you leverage: the home has sat on the market or had price drops, it needs work most buyers won't take on, the seller needs to move, or comps show it's overpriced. In a hot market with multiple offers, skip it.
A low offer works when the seller has a reason to say yes. Your job is to find that reason before you write the number. Here's what I look for.
- It's been sitting. A listing that has been on the market for months, or has dropped its price more than once, tells you the seller's original number didn't work. For reference, the typical home that sold in the four weeks ending September 13, 2026 spent 46 days on the market, according to Redfin. A house sitting well past that is a house where the seller's hope is running into reality. If you want to find these on purpose, I break down the search filters in how to find houses to flip on Zillow.
- It needs work. Outdated kitchens, a bad roof, foundation questions, a house full of stuff. Most regular buyers want to move in and unpack, so a project shrinks the pool of people who'll make an offer. Fewer buyers means more room for yours.
- The seller needs to move on. A job relocation, a divorce, an inherited house nobody wants to manage, a seller moving closer to family. Motivated sellers care about speed and certainty, sometimes more than squeezing out the last dollar.
- The comps say it's overpriced. If recently sold homes nearby don't support the asking price, your "low" offer may just be the real price, like the example in the last section.
- Nobody else is bidding. This is the one most people skip. I ask the listing agent how the activity has been, whether the offers are coming from homeowners or investors, how many there are, and when the seller plans to review them. Homeowner offers usually come in higher, because people buying a place to live will pay more and get emotionally attached. If it's only a couple of investors, or nobody at all, you have room to go low.
The bigger market is on your side right now too. In August 2026, the total number of U.S. homes for sale hit its highest level since 2020, according to Redfin. More homes for sale means more sellers competing for fewer buyers, and that's when low offers get taken seriously.
And here's when I don't lowball: a fresh, fairly priced, move-in-ready house in a neighborhood where everything gets multiple offers. Offering 20% under on that house doesn't make you a tough negotiator. It makes you the offer nobody responds to. I cover those situations in the risks section below.
How Much Should You Offer On A House As A Lowball Offer?
Offer what the numbers support, not a set percentage. Work out your maximum offer from the fixed-up value minus repairs, costs and profit, then open a bit below it. On a $150,000 listing in my example, the math capped the offer at $127,000, about 15% below asking.
"Just offer 20% under" is the worst advice in this business. Twenty percent under might be too high on one house and laughable on the next, because a percentage knows nothing about the roof, the kitchen or what the comps say. Your offer has to come from math.
The number you're solving for is your maximum allowable offer (MAO): the most you can pay and still make the deal work for whoever ends up fixing the house. I walked Tim, a member of our team who was learning to wholesale, through this exact calculation in our deal calculator. Here's the house:
- After repair value: $200,000
- Repairs: $25,000
- Holding costs for a 3-month project: property taxes of about $2,500 a year, insurance around $150 a month, utilities around $100 a month. That's $1,375 for the three months.
- Closing costs on the purchase: about 1% of the price. I bump that to 2–3% on very cheap houses.
- Selling costs on the resale: $10,000 (5% of the after repair value) in this example: 1.5% to the listing broker, 2.5% to the buyer's broker and 1% in closing costs. Commissions are negotiable, so plug in your own.
- My wholesale fee: $10,000
- The list price: $150,000
Then the question that decides everything: what does your buyer need to make? The cash buyer on this deal needed at least $25,000 in net profit and a 15% return on investment (ROI), meaning net profit divided by everything they put into the deal. Here's what happens as the purchase price comes down:
| My Offer | Buyer's Total Investment | Buyer's Net Profit | Buyer's ROI | Meets $25K / 15%? |
|---|---|---|---|---|
| $150,000 (asking) | $187,875 | $2,125 | 1.1% | No |
| $140,000 | $177,775 | $12,225 | 6.9% | No |
| $130,000 | $167,675 | $22,325 | 13.3% | Close, but no |
| $127,000 (max offer) | $164,645 | $25,355 | 15.4% | Yes, the ceiling |
| $120,000 (opening offer) | $157,575 | $32,425 | 20.6% | Yes, with room |
Total investment = purchase price + my $10,000 fee + repairs + holding costs + purchase closing costs. Net profit = $200,000 resale − $10,000 selling costs − total investment. This is an example; your numbers will be different.
At asking, the deal makes $2,125 on almost $188,000 at risk. You'd earn more leaving the money in the bank. At $127,000, the deal works. That's 15% below asking, a "lowball" by most definitions, and it's simply the highest price the math allows.
That gives you three numbers to negotiate with:
- Open at $120,000. That's 20% under asking, but it leaves room to come up.
- Hold firm at $127,000, your max offer.
- Stretch only by cutting your own profit. At $132,000, the deal still works if I take a $5,000 fee instead of $10,000. It's better to make something than nothing and lose the deal to someone else. If you're the one flipping it, the stretch comes out of your profit instead.
📓 From The Field
I've wholesaled dozens of deals to one cash buyer whose minimum on every deal was $25,000 in net profit and a 15% ROI. Both boxes had to be checked or he'd pass. Learn your buyers' criteria before you make offers, because it decides your max offer. Criteria vary by buyer and market.
What About The 70% Rule?
The 70% rule is the back-of-the-napkin version: 70% of the after repair value, minus repairs. On this house that's $200,000 × 70% − $25,000 = $115,000 for the cash buyer. Take my $10,000 fee out of that, and I could only offer $105,000. The full calculation supports $127,000, which is $22,000 more room on the same house.
The rule is fine for a quick check, but if you're competing with other investors, run the real numbers. You can learn how the MAO formula and the 70% rule compare in more depth, or use our wholesale real estate calculator to run your own.
Watch me work this example down to the max offer
Calculate Your Max Offer Before You Make A Low One
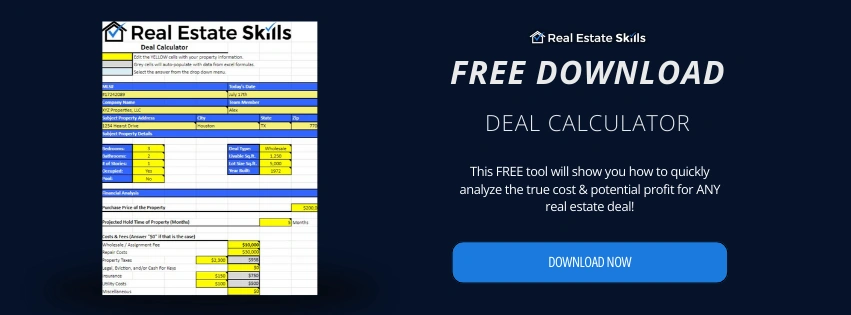
A lowball offer only works when you can back it up. Our free Excel deal calculator runs the same math from this guide: enter the after repair value, repairs, holding costs, closing and selling costs, and your fee, and it shows the buyer's total investment, net profit and return at any purchase price. Find your max offer and your opening number before you ever call the agent.
Read Also: MAO Formula: The (Ultimate) Guide
How To Make A Lowball Offer On A House
To make a lowball offer on a house, check comps, call the listing agent to learn about repairs, motivation and competing offers, then run your numbers. Deliver the offer on a second call with clean terms, send a complete written package, and follow up until the seller decides.
Most people think the hard part of a lowball offer is saying the number out loud. It isn't. The hard part is everything before it. When you do the setup right, presenting a low cash offer feels calm and professional, and agents treat it that way. Here's the exact process my team and my students use on houses listed on the MLS. If you're dealing directly with a seller, the same steps work. You just ask the seller instead of the agent.
This walkthrough is educational, not legal advice. Agency, disclosure and call-recording rules vary by state, so confirm what applies where you buy with a licensed real estate attorney before you start making offers.
Step 1: Run A Quick Comp Check Before You Call
Spend five minutes on comps before you pick up the phone. Look at what's active, pending and sold nearby so you have a feel for the house's value and can tell when an agent's numbers don't add up.
You don't need a full analysis yet. You need enough context to ask smart questions and recognize a bad answer. If the agent tells you a distressed house is worth what the renovated ones down the street sold for, you'll know.
Step 2: Call The Listing Agent For Information, Not An Offer
Your first call is a discovery call. Ask about the seller's reason for selling, the condition and major repairs, what the house could be worth renovated, how many offers there are and from whom, and what price would get it under contract.
Never make your offer on this call. If you're running numbers in your head while the agent talks, you're not listening, and the details you miss are the ones that justify a low price. The questions I want answered:
- Why is the seller selling? A divorce, a move, an inheritance. The reason tells you what matters to them besides price.
- What condition is it in, and are there any major issues? Ask specifically about the roof, foundation and electrical.
- What could it be worth fully renovated? If the answer is close to the list price, the listing is priced as if the work were done.
- How's the activity? How many offers, from homeowners or investors, and when the seller plans to decide.
- What price would get it under contract today? Then stay quiet and let them answer. If they dodge, ask for a ballpark. If they name a number, ask how flexible it is and whether the seller will look at offers below it. Now your low number becomes their idea.
- Are there terms the seller wants? A fast close, a slow close, extra time to move out.
My team also asks whether the listing agent would be open to representing us on the offer. That gives the agent a reason to help the deal happen. But rules on one agent representing both sides vary: some states ban it, and the rest generally require written, informed consent from both buyer and seller. Agents who use the MLS also have to sign a written agreement with a buyer before touring a home with them, a rule in place since August 2024. Know your state's rules before you ask.
If you're wholesaling, follow your state's disclosure rules from the very first conversation. Some states now require you to tell sellers in writing that you're selling your contract rather than buying to keep. Check whether wholesaling is legal in your state and what it requires before you make offers.
Know What To Ask Before You Make A Low Offer
The details that justify a low offer come from the listing agent, if you ask the right questions. Our free Discovery Call Script gives you the questions we use on MLS listings: the seller's reason for selling, the property's condition and major issues, what it could be worth renovated, how many offers are in and from whom, and what price would get it under contract. Download it, and make the call before you make the offer.
Step 3: Price The Repairs Into Your First Number
Use everything the agent told you about repairs to set your offer before you submit it. A calculated low offer up front beats a high offer you try to renegotiate later, which destroys your credibility with the agent.
This is where most beginners mess up. They offer too high to "get something under contract," then come back after the inspection asking for $20,000 off. Agents remember that. If the agent tells you the AC is out, that alone could be a $5,000 to $10,000 fix, so it goes in your number now, not later.
📓 From The Field
Torreine, one of our acquisitions associates, called the listing agent on a brand-new fixer listing. By asking simple questions and then letting the agent talk, she learned the sellers were moving to be closer to their son, the kitchen and bathroom both needed to be redone, the AC wasn't working, and the sellers were hoarders with a house full of belongings. That's the kind of detail that almost never comes out over email or text. Every piece of it lowered what the house was worth to an investor, and it showed which terms might matter to the seller, like extra time to move or help clearing out the hoarder house. Where she could improve was the price question: the agent talked around it, and the move is to ask again for a ballpark.
Watch the part of the call where the agent explains how much work the house needs
Step 4: Run Your Numbers And Set Your Opening And Max Offer
After the call, plug the agent's details into your numbers and set two prices: the opening offer you'll present and the maximum you'll pay. Decide them before the second call so you never negotiate against yourself on the phone.
I walked through the full math above in how much to offer. The point here is timing: your opening and your max are set before you dial, not in the middle of a conversation when the agent pushes back.
Step 5: Make The Offer On A Second Call
Call the agent back and state your offer once: the price, all cash, a short inspection period and a fast close. Then stop talking. Don't over-explain or apologize. If they hesitate, ask where the offer would need to be to make it work today.
Silence is the hardest part. Say the number, then let the agent respond. I share the exact wording I use in the next section on what to say.
📓 From The Field
After a discovery call and a visit to the property, my student Tyler called the listing agent back and kept it to a sentence: they could come in at $335,000, and would she represent them on the offer. He didn't justify the number or apologize for it. The agent wasn't offended. She told him the seller was hoping for more, encouraged him to come in at his highest and best, and when he said $335,000 was his max, she asked him to email the terms so she could write it up. That's what a low offer sounds like when the groundwork is done.
How to Make a LOW Cash Offer on a House [LIVE CALLS]
Alex breaks down two real calls with listing agents, from the first questions on the discovery call to presenting a $335,000 cash offer on the second.

Jump to the question that gets the agent to name a price or Tyler's $335,000 offer call.
Step 6: Send A Clean, Complete Written Offer
Email the agent your offer terms with everything they need to write the contract: the property address, your buying entity, price, deposit, closing date, inspection period and title terms. Attach proof of funds and your entity documents before they have to ask.
I learned this one the hard way over thousands of offers. When an agent has to chase you for a missing document, you look like an amateur, and if two offers come in at the same price, the agent trusts the one that made their job easy.
Two rules here. First, your proof of funds letter has to show money that's actually available to you for this purchase, from your own account or a lender's commitment in your name. Second, read the contract the agent sends back before you sign it. Check the price, the dates and especially your inspection period, because that window, and when your deposit stops being refundable, depends on your contract and your state. And remember that you don't have a deal until the seller signs too.
Step 7: Follow Up Until The Seller Decides
After you send the offer, text or call to confirm the agent received it, then follow up regularly until the seller's review date. If the answer is no, stay professional and stay in touch, because sellers who reject a low offer often come back after a few more weeks on the market.
An offer in is better than no offer. Even when this house doesn't work out, you've just built a relationship with an agent who lists houses like it, and that's often worth more than the deal. Agents who list fixer-uppers list them again and again, and the investor they already know gets the next call.
You Know How To Make The Offer. Now Learn Where The Deals Come From.
A lowball offer only works on the right property. Our FREE Training walks you through the system Alex Martinez uses to find discounted houses, make offers that get accepted, and wholesale or flip them without spending money on marketing. No experience needed, and it works in any market. Watch it today, then make your next offer count.
Watch The FREE Training →What To Say When You Make A Lowball Offer
When you make a lowball offer, state the price and terms once, confidently, then stop talking. Lead with the work you've done ("after accounting for the repairs..."), don't apologize or over-explain, and if the agent pushes back, ask where the offer would need to be to make it work.
Agents can hear nerves. If you sound unsure about your own number, they'll assume it's not serious, and they won't fight to get it in front of the seller. A conversation with an agent is like a dance: you lead with questions, you let them talk, and you don't step on their toes. Here are the lines I use at each point.
🗣️ The Lines I Use On The Call
- Opening the call: You're not cold calling. Their number is on the listing, and they expect investors to call.
"Hey Lisa, this is Alex with ABC Homes. How are you doing today? I'm calling about your listing on Main Street. Do you have a few minutes, or is there a better time today?" - Asking for the number: Ask, then stay silent and let them answer.
"What price would I need to come in at today to get this under contract?"
If they won't say: "It never hurts to ask. Is there a ballpark?" If they give you a number: "How flexible is that? Would the seller look at offers below it?" - Ending the discovery call: Set the next step with certainty.
"Thanks, Lisa. I'm going to run the numbers with my team, and I'll call you back with a cash offer." - Presenting the offer on the second call: Lead with the work, then the terms, then the price.
"I just finished going through the property with my team: the repairs, the costs, everything it'll take to bring it up to today's market. We can do all cash, a 7-day inspection and a 14-day close, at $445,000."
Then stop talking. Hold your breath if you have to. - If they say no or maybe: "Understood. Where would the offer need to be today to make this work?"
- If they say yes: "Great. I'll email the offer terms with our proof of funds right after this call."
| Instead Of This | Say This | Why |
|---|---|---|
| "I know this is really low, sorry..." | State the number and stop | Apologizing tells them you don't believe in your own price |
| "The place is a dump" | "The kitchen, bathroom and AC all need to be redone" | Specific repairs are facts. Insults make the seller dig in. |
| "I'll try to get you an offer, maybe today" | "I'll call you back with a cash offer" | "Try" and "maybe" sound like you won't follow through |
| Talking through your whole spreadsheet | One sentence on the work, then the terms and price | Over-explaining invites the agent to argue each line |
| "What's the lowest they'll take?" | "What price would get it under contract today?" | Same question, but it sounds like a buyer, not a bargain hunter |
Two things I won't do, no matter how low the offer. I won't misrepresent what's wrong with a house, and I won't misrepresent who I am or what I plan to do with it. A lowball offer works because the numbers are honest. The moment you invent problems or fake a story, you've traded a negotiation for a reputation problem.
📍 Record Your Calls (With Consent)
The fastest way I've seen people improve is listening back to their own calls: where they talked too fast, interrupted, or let a question slide. But get permission first. Federal law requires at least one party's consent to record a call, and about 11 states require everyone's consent. If you and the agent are in different states, the safest move is to ask everyone on the call before you hit record. Check state call-recording consent laws before you start.
How To Make A Low Offer More Attractive Without Raising Your Price
Make a low offer more attractive by giving the seller things they value besides price: an all-cash offer, a fast or flexible closing date, a short inspection period, no repair requests, or extra time to move out. Adjust your terms before you raise your number.
Price is only half of an offer. The other half is terms: how you'll pay, when you'll close, what you'll ask for and how much hassle the seller has to deal with. When a seller pushes back on a low number, my first move isn't raising the price. It's finding out what else they need. If I planned a 14-day close and the seller needs to be out in 7, I close in 7. That costs me almost nothing and can be worth more to them than a few thousand dollars.
This is why the discovery call matters. Once you know the seller's reason for selling, you can build terms around it. In Torreine's call, the sellers were moving to be near their son and had a house full of belongings. A buyer who offers them time to move and help clearing the house is solving their actual problem, not just haggling.
| Term | What The Seller Gets | Your Trade-Off |
|---|---|---|
| All cash | No loan to fall through and no appraisal to come in short | You need real funds or a lender commitment lined up |
| Close in 14 days or sooner (or on their timeline) | Speed and certainty, or a later date if they need time | A fast close leaves you less time to arrange money and paperwork |
| Short inspection period (7 days) | Less time sitting in limbo | Less time to verify repairs and line up your buyer |
| No repair requests or credits | No second negotiation after they say yes | You have to price every repair in up front |
| Leaseback (they stay 2–4 weeks after closing) | Their sale money in hand before they have to move | You're the owner while someone else lives there. Put it in writing. |
| Extra move-out time or help with belongings | One less thing to manage, especially in an estate or hoarder situation | Cleanout costs and delays come out of your numbers |
A few rules I follow with terms:
- Only offer terms you can actually deliver. Promising a 7-day close you can't fund is worse than offering a lower price honestly.
- Don't stack asks on a low price. A low offer that also asks for repairs, credits and a long inspection gives the seller three reasons to say no. Keep it clean.
- Shorten your inspection period carefully. If other investors are offering 5 days, I'll sometimes offer 4. If you're new, keep a full inspection period. It's your way out of a deal that turns out worse than you thought, and when your deposit stops being refundable depends on your contract and your state. I break down how those clauses work in the wholesale real estate contract guide.
- Get leasebacks and occupancy terms in writing, with an attorney's review. Who pays utilities, who's responsible for damage and what happens if the seller doesn't leave on time all need to be settled before closing.
The pattern is simple. Learn what the seller needs, give it to them where it's cheap for you, and protect your price.
Can You Lowball A Foreclosure?
Yes, you can lowball a foreclosure. Bank-owned homes are often good candidates because the seller prices off data, not emotion. Check the time on market and price history, back your number with repair costs, and know some Fannie Mae and HUD homes give owner-occupants first priority.
Foreclosures are some of the best houses to make low offers on, because the seller doesn't live there and doesn't love it. A bank that took a house back wants it off its books. It isn't attached to the kitchen it remodeled in 1998. But "foreclosure" covers a few different situations, and they work differently:
- Bank-owned (REO) homes. After a foreclosure, if nobody buys the house at auction, the lender takes it back and lists it with an agent. These REO properties are the classic lowball target. Banks get more flexible the longer a house sits and the more price cuts it takes.
- Short sales. The owner still owns the house but owes more than it's worth, so their lender has to approve any sale below the loan balance. You can offer low, but the lender sets the floor, and approval can take weeks or months.
- Pre-foreclosures. The owner has fallen behind but still owns the house. There's no bank to negotiate with yet. You're dealing with a stressed homeowner, which calls for honesty and care, not pressure.
- Government-backed foreclosures (Fannie Mae and HUD homes). These come with rules that matter for investors, covered next.
📍 Know When Investors Are Allowed To Bid
Some foreclosures don't take investor offers at first. Under Fannie Mae's First Look program, only owner-occupants and public entities can make offers on its HomePath homes during the first 20 days on the market. HUD gives owner-occupants, HUD-approved nonprofits and government buyers a 30-day exclusive period on homes listed as "insured" or "insured with escrow" before investors can bid. These windows can change, so check the countdown on the listing. As an investor, you're watching for those listings to open up, ideally after nobody has bought them at the opening price.
Before I write a low offer on a bank-owned house, I want answers to these questions:
- How long has it been on the market, and how long since the last price cut?
- Has the listing agent hinted the bank will look at lower offers?
- How does the list price compare with the comps for the house's actual condition?
- What will the repairs really cost? Foreclosures often sat empty, so plan for surprises.
- How strong are my terms? Banks like cash, proof of funds up front and a clean, quick close.
One practical tip: the agents who list bank-owned houses list distressed properties all the time. Treat that first call like any discovery call, be the easy, professional buyer, and you'll often get the next one before anyone else does. Expect banks to have their own addenda and offer deadlines. Read every page, and remember the house is sold as-is.
Risks Of A Lowball Offer And When Not To Make One
The biggest risks of a lowball offer are losing the house to another buyer, getting ignored by the seller and agent, and burning a relationship you'll need later. Don't lowball a fairly priced, move-in-ready home in a competitive market, or a home you'd be heartbroken to lose.
I make low offers for a living, and I'll still tell you they're the wrong move a lot of the time. Here's what can go wrong and how to keep it from happening.
| Risk | What It Looks Like | How To Limit It |
|---|---|---|
| You lose the house | Another buyer offers closer to asking and the seller takes it | Only lowball where the signals give you leverage, and decide your max offer before you start |
| You get ignored | No counter, no call back, your offer goes to the bottom of the pile | Back the number with repairs and comps, and send a complete, professional offer |
| You burn the agent | The listing agent stops taking your calls on future listings | Be honest, be easy to work with, and never renegotiate a price you could have priced in up front |
| The seller says yes too fast | A quick acceptance on a very low number, and you haven't found out why | Use your inspection period. Fast yeses sometimes come with problems the seller already knows about. |
| You can't back out cleanly | You decide to walk after your inspection period ends | Track every deadline. Outside your contingencies, your deposit is usually at risk. |
The first risk is bigger than beginners expect. Even in today's slower market, about 1 in 4 U.S. homes (24.1%) sold above their list price in September 2026, according to Redfin. Those are the houses where a lowball offer gets you nothing but a "no."
📍 When I Wouldn't Make A Lowball Offer
- The house is fairly priced, updated and fresh on the market in a neighborhood where homes get multiple offers. Everyone else will be at or above asking.
- The comps support the asking price. If the math says the house is worth what they're asking, a low offer isn't negotiating. It's just wrong.
- There's a "highest and best" deadline with several offers in. Your low number won't be the one they pick.
- You can't deliver the terms that make a low offer work, like cash or a fast close. A low price with a slow, shaky offer gives the seller no reason to say yes.
- You're buying a home to live in, and you'd be crushed to lose it. This one's for homebuyers, not investors. If this is the house, a few thousand dollars spread over a 30-year mortgage is a small monthly difference. Losing it means starting your search over. An investor can walk away from any deal. You might not want to.
Low offers are a tool. Use them where the numbers and the seller's situation support them, and skip them where they don't.
Should You Accept, Reject, Or Ignore A Lowball Offer?
Don't ignore a lowball offer. Respond to every one: accept it if it's close to what comps support and the terms are strong, counter if there's room to negotiate, and reject it politely only if it's far below value and you have data to back your price.
I'm on both sides of this. I make low offers when I'm buying, and when I sell a finished flip, I get them too. Here's how I'd handle one as a seller.
- First, don't take it personally. Lowball offers come from investors running numbers, from buyers who don't know the market yet, and from people testing how firm you are. None of them are a judgment of your home. A low offer still means someone wants to buy it.
- Second, check whether it's really a lowball. Compare it with recent sales of similar homes nearby, in similar condition. If several offers come in around the same "low" number, or your house has sat for weeks with few showings, the market may be telling you the asking price is the problem.
- Third, compare what you'd actually walk away with, not just the price. A lower offer with better terms can put more money in your pocket.
💡 A Lower Offer That Nets More
- Offer A: $300,000 with a loan. The buyer asks for $10,000 in repair credits and $6,000 toward their closing costs, and the deal depends on an appraisal. You'd net about $284,000 before your own selling costs, if the appraisal comes in.
- Offer B: $285,000 all cash, as-is, closing in 14 days. You'd net $285,000 before your own selling costs, with no appraisal and no loan risk.
Your own selling costs (commissions, title, transfer taxes) apply to both offers, so the comparison holds. This is an illustration. Your real numbers depend on your contract and market.
| Your Three Real Options | When It Makes Sense |
|---|---|
| Accept | The offer is close to what comps support, the terms are strong (cash, fast close, no repair asks), or you need speed and certainty more than the last few thousand dollars |
| Counter | There's a real gap, but the buyer looks serious. This is the right answer most of the time. |
| Reject | The offer is far below what the comps support, you have the data to prove it, and the buyer gave no reason behind the number. Even then, say no politely and leave the door open. |
| Ignore | Never. Silence ends the negotiation and tells the buyer you aren't serious about selling. |
What Does "No Lowball Offers" Mean?
You'll see it on listings and on Facebook Marketplace ads. It means the seller considers the price firm, or close to firm, and doesn't want to spend time on offers far below it. It doesn't stop anyone from making one. It's a signal of how the seller will likely respond.
Will Your Agent Show You A Lowball Offer?
They should. NAR's Code of Ethics requires Realtors to present offers objectively and as quickly as possible, and listing brokers have to keep submitting every offer to the seller until closing unless the seller waives that in writing. Many states have their own rules on top of that. If you'd rather not see offers below a certain number, tell your agent in writing.
This is general guidance, not legal or financial advice. Your listing agreement and your state's rules control how offers are handled, so talk with your agent or a real estate attorney about your specific situation.
How To Counter A Lowball Offer On Your House
To counter a lowball offer, respond quickly and politely, find out what's driving the buyer's number, then counter with a price backed by comps, or hold your price and offer better terms. Add a short deadline, and keep the door open even if the first round goes nowhere.
- Respond fast, in writing, and without emotion. A same-day reply tells the buyer you're serious and keeps their attention on your house instead of the next one.
- Find out what's behind the number. Have your agent ask the buyer's agent what's driving the offer. If it's repairs, ask which ones and how they priced them. If it's comps, ask which sales they used. You can't answer an objection you haven't heard.
- Re-check your own numbers. Pull the latest sold comps and work out the lowest net amount you'd accept after your selling costs. Decide it before you counter, the same way I set my max before I make an offer.
- Counter with a reason, not just a number. Come down some, but not much, and tie it to something real: the new roof, the sold comp two streets over, the fact that you've had showings all week. Or hold your price and give on terms instead, like a closing date that works for them or leaving the appliances.
- Put a deadline on it. Twenty-four to 48 hours is common. It keeps your house from becoming the backup option while the buyer shops around.
- Keep the door open. If it goes nowhere, end on good terms and keep the buyer's contact information. If your house is still on the market in three weeks, that buyer may be your best lead.
What a counter can sound like (through your agent):
"Thanks for the offer. Based on recent sales of similar homes nearby, the seller can do $289,000 with a 21-day close. This counter is good until 5 p.m. Friday."
It's short, it's polite, it gives one reason and one deadline, and it doesn't argue with the buyer's math.
What Happens On The Investor's Side When You Counter
When a seller counters me, the first thing I do is compare their number with the max offer I set before I ever called. If the counter is at or under my max, we can probably make a deal. If it's over, I'll see whether different terms close the gap, like a faster close or taking the house with everything left in it. If it's still over my max, I walk, politely, and I'll check back in a few weeks.
So if an investor tells you they're at their max, it often isn't a bluff. The math stopped working. Your choice is whether their certainty and speed are worth more to you than waiting for a higher offer that may or may not come. Run the net numbers from the last section and decide with the data, not with your pride.
Read Also: Best Companies That Buy Houses For Cash
Lowball Offer FAQs
Final Thoughts On Lowball Offers
A lowball offer isn't a trick, and it isn't an insult. It's a number with a reason behind it. Get the reason right (the comps, the repairs, the seller's situation), and the number takes care of itself.
The investors who get great deals aren't the ones with the boldest offers. They're the ones who did the discovery call, ran the math, said their price calmly and followed up. Plenty of their offers still get rejected, and that's normal. Every deal is a deal at the right price, and the only way to find the right price is to make offers.
Here's your next step. Pick three listings in your area that have sat on the market longer than usual or have had a price cut. Run each one through the numbers from the how-much-to-offer section, call each listing agent with the discovery questions above, and make at least one offer this week. An offer in is better than no offer.
Your Next Low Offer Could Be Your First Deal.
Most people who read about lowball offers never send one. The ones who close follow a proven process: find the discounted property, run the numbers, make a confident offer, and get it under contract. Our FREE Training shows you the exact system Alex uses to wholesale and flip houses without paying for marketing. Watch it today, then go make an offer.
Watch The FREE Training →
About The Author
Founder & CEO, Real Estate Skills
Alex Martinez is the Founder & CEO of Real Estate Skills. He has wholesaled and flipped houses for over 14 years, been part of 1,000+ real estate transactions, and personally acquired 55+ residential investment properties. He has trained 6,000+ investors nationwide and teaches the Real Estate Skills community how to find, analyze and negotiate deals.
Real Estate Skills is not a law firm, and the information in this article is provided for educational purposes only. It does not constitute legal, tax, or financial advice. Real estate laws, agency rules and contract requirements vary by state and change over time. Real estate investing carries risk, and the examples in this article, including any results, do not guarantee future outcomes. Always consult a licensed real estate attorney and your own financial advisors before making an offer or entering into a contract.
👉FREE Training
How To Consistently Wholesale, Flip Houses, & Invest In Rental Properties From The MLS
(Without Spending $1 On Marketing)

Alex Martinez, the founder of Real Estate Skills, is known for his strong, practical expertise in real estate, starting from a beginner with no family connections in the industry to acquiring over 55 real estate deals, including wholesale and flips, within his first year.
He has dedicated his career to providing cutting-edge education and resources for real estate professionals. He emphasizes the importance of self-taught knowledge through mentors, books, and hands-on experience.
His journey from earning a modest income to becoming a successful real estate entrepreneur and educator showcases his expertise and dedication to the field.

Ryan Zomorodi, co-founder and COO of Real Estate Skills, leverages his experience from a diverse background in real estate investment, construction management, and entrepreneurship to provide comprehensive education in the real estate sector.
His expertise is rooted in hands-on experience, extensive industry knowledge, and a commitment to empowering others through education.
Ryan's journey reflects a blend of practical experience and entrepreneurial success, contributing to his role in developing a platform that educates and supports aspiring real estate professionals.
Read Ryan's Full Bio >>
